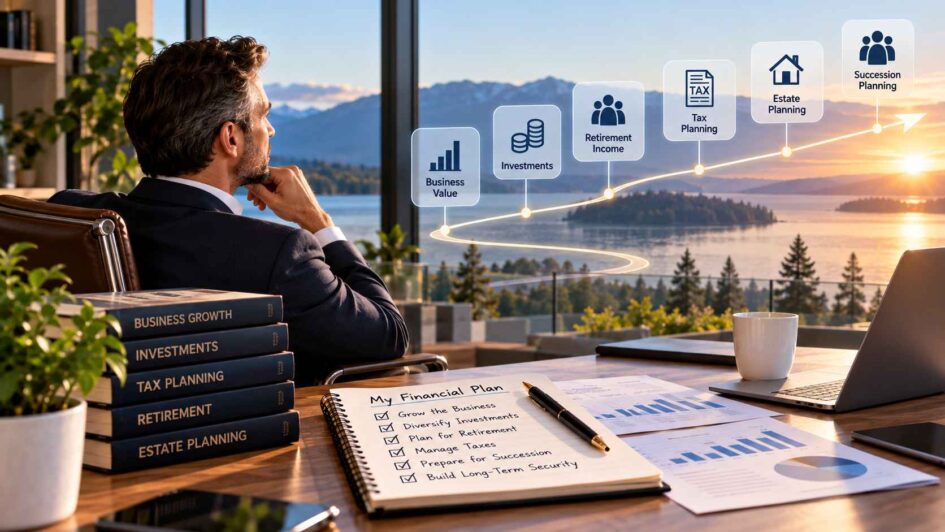
Building a successful business can create opportunities that extend far beyond the company itself. Strong revenue can support a family, fund future investments, create jobs, and potentially build significant personal wealth.
But business success and personal financial security are not automatically the same thing.
For many entrepreneurs, a large portion of their net worth remains tied to the company. That can make personal finances vulnerable to changes in business performance, market conditions, an unexpected sale, or a change in the owner’s ability to continue working.
The goal is not to separate the business completely from personal finances. Instead, business owners can benefit from regularly looking at how company success fits into their broader financial plan.
Business Success Does Not Automatically Equal Financial Security
A profitable company can generate substantial income without necessarily creating a diversified personal financial position.
An owner may reinvest most available cash into hiring, equipment, real estate, inventory, technology, expansion, or working capital. Those decisions can support the business, but they may also mean that relatively little wealth has been built outside the company.
This becomes particularly important when an owner begins thinking about retirement or eventually leaving the business.
A business may have significant value, but that value may not immediately translate into accessible personal income. The timing and structure of a future sale are uncertain, and an owner may ultimately choose a transition that looks very different from the original plan.
For business owners who want to connect business decisions with their broader financial objectives, Exponent Investment Management provides wealth management and financial planning services for professionals, business owners, and families.
The important first step is understanding the complete financial picture rather than viewing the business in isolation.
The Risk of Concentrated Wealth
Entrepreneurs often accept concentration as part of building a company.
If the business is performing well, putting additional resources into it can seem logical. The challenge is that the owner may eventually have most of their financial future dependent on one asset.
That concentration can affect planning for retirement, major purchases, family needs, and unexpected events.
Building personal investments alongside the business can provide another source of financial flexibility. The appropriate approach depends on factors such as income, time horizon, risk tolerance, liquidity needs, existing assets, and personal objectives.
Diversification also does not necessarily mean reducing commitment to the business immediately. It can be a gradual process of considering how much wealth should remain connected to the company and how much can be developed elsewhere over time.
For an entrepreneur, that distinction can become especially important as the company matures.
Building Personal Investments Alongside the Business
A growing business can consume an owner’s attention, but personal financial planning should not necessarily wait until the company is ready to be sold.
Business owners can periodically review the assets they hold outside the company and consider whether those assets are aligned with their longer-term goals.
That review might include registered savings, investment accounts, real estate, cash reserves, insurance, and other assets.
The objective is not simply to accumulate more assets. It is to create a financial structure that supports the owner’s broader plans.
For example, someone who expects to remain involved in the company for another decade may have different priorities from someone who expects to reduce their involvement within a few years. Similarly, an owner with significant personal debt may have different planning considerations from someone with substantial liquid investments.
The right strategy depends on the individual circumstances rather than a universal formula.
Planning for Retirement
Retirement planning for a business owner can be more complicated than simply choosing a target retirement age.
An entrepreneur may have income from the company, investment income, registered retirement savings, government benefits, real estate, or eventually the proceeds of a business transition.
The challenge is understanding how these different sources could fit together.
The Government of Canada’s retirement planning resources emphasize considering how much income may be needed, when retirement may begin, and the different sources of retirement income available to an individual. Canada.ca retirement planning guidance
For business owners, this exercise can also highlight the importance of preparing for different scenarios.
What happens if the business is sold later than expected? What if the owner wants to work part-time after stepping away? What if a family member takes over rather than an outside buyer?
Planning around several possibilities can provide a clearer framework without requiring the owner to predict exactly what the future will look like.
Tax and Estate Considerations
Business and personal financial decisions can have tax and estate implications, particularly when significant assets or ownership interests are involved.
An owner may need to consider how investments are held, how business interests could eventually be transferred, and how personal assets should be organized for family or estate purposes.
Estate planning can become particularly important when a business represents a major part of the family’s wealth.
Questions may include who should receive ownership interests, who can make financial decisions if the owner becomes unable to do so, and how the business should be handled after the owner’s death.
These matters can involve legal and tax rules that vary according to the individual’s circumstances and jurisdiction. Business owners should therefore coordinate with appropriate legal, tax, and financial professionals rather than treating estate planning as a one-time paperwork exercise.
Preparing for Business Succession
Succession planning is closely connected to personal financial security because the way a business changes ownership can affect the owner’s future finances.
Some owners may sell to another entrepreneur. Others may transfer the company to family members, sell to employees or partners, or gradually reduce their involvement while retaining an ownership interest.
Each approach can have different financial consequences.
The Government of Canada identifies business succession planning as an important part of preparing for ownership transitions, including situations where a business is sold or transferred to relatives or another entrepreneur.
For an owner, the key question is not simply, “Who will take over?” It is also, “What will my financial life look like after the transition?”
Answering that question early can help identify potential gaps between the expected business transition and the owner’s personal goals.
Bringing the Pieces Together
Personal wealth planning becomes more useful when business, investment, retirement, tax, estate, and succession decisions are viewed as connected rather than separate topics.
A business owner might otherwise make perfectly reasonable decisions individually while missing the bigger picture. Reinvesting heavily in the company may make sense operationally, for example, while simultaneously increasing personal financial concentration.
Professional planning can help bring those decisions into the same conversation. A financial planning strategy for business owners can examine how current cash flow, personal investments, retirement objectives, business value, and future ownership plans interact.
The purpose is not to predict investment returns or guarantee a particular financial outcome. It is to give the owner a clearer framework for making decisions as circumstances change.
Building Security Beyond the Business
Business ownership can be one of the most rewarding ways to build wealth, but it also creates a unique financial dependency.
The company may be the owner’s largest asset, biggest source of income, and most important long-term project. That makes it worth considering what happens when the owner eventually wants to step back.
Building personal investments, reviewing retirement needs, considering tax and estate issues, and preparing for succession can help create a more complete financial picture.
Most importantly, these conversations do not need to wait until an exit is imminent. Business owners can revisit their personal financial position as the company grows and their goals change, creating a planning process that evolves alongside the business.